Did China's Robot Density Really Overtake Japan's?
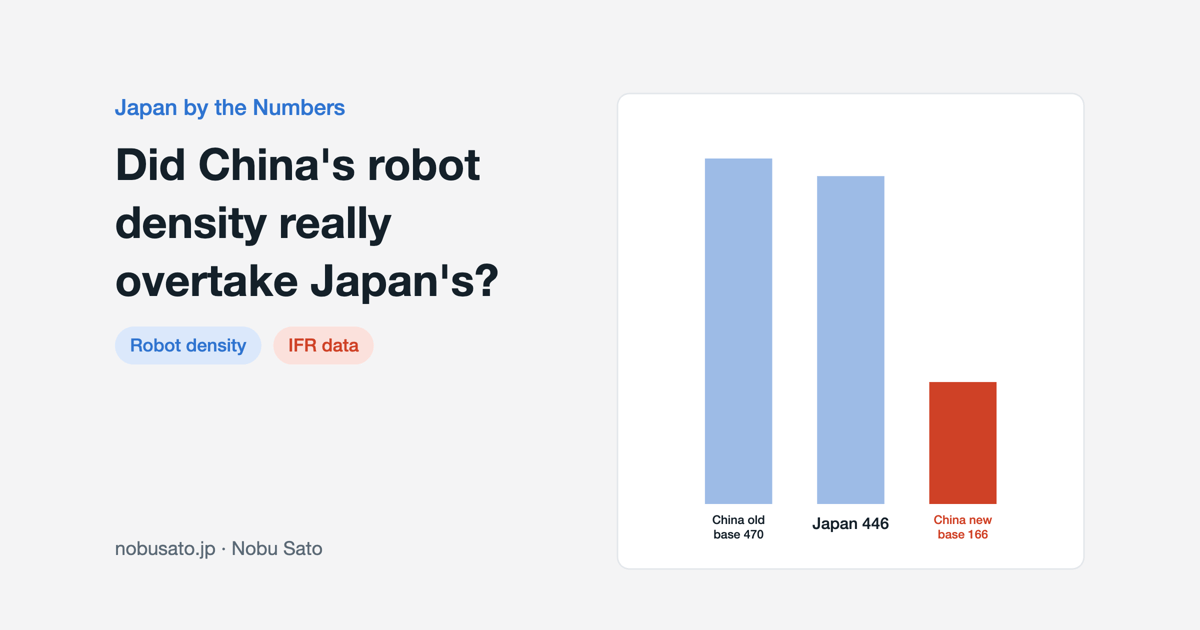
On the latest IFR numbers, China is far behind Japan in robot density. Where China is ahead is volume, by a lot. The famous 2023 figure of 470 robots per 10,000 factory workers came from a narrow count of Chinese workers. In April 2026 the International Federation of Robotics (IFR) put China's 2024 figure at 166. Japan's was 446.
If you sell automation, logistics or service robots into Japan, or you run a Japan entity for a Chinese hardware company, this matters. The two numbers point you at different competitors and different customers.
What robot density counts, and what it leaves out
Robot density is the number of industrial robots in operation in a country, divided by the number of people employed in manufacturing, scaled to 10,000 employees. The IFR publishes it with its annual World Robotics report. It is meant to compare how automated factories are across countries.
Three limits are easy to miss.
It counts manufacturing only. A warehouse isn't a factory, so the autonomous carts moving pallets in a Japanese distribution center are not in it.
It counts industrial robots only. Service robots, such as delivery, cleaning, serving and care robots, are tracked separately by the IFR and are excluded. The sectors where Japan is shortest of people, logistics and elderly care, are mostly invisible in this metric.
And it is a ratio. If factory employment falls and nobody adds a single robot, density still goes up. The IFR says Japan's density has grown about 5% a year since 2019. How much of that is new robots and how much is a shrinking, aging factory workforce, the press release does not say. I would not read Japan's rise as pure investment.
How China went from 470 to 166
The denominator changed. In its release of April 8, 2026, the IFR said China's 2024 density of 166 is based on updated labor market data from China's National Bureau of Statistics. That puts China 22nd in the world and 6th in Asia, still up 17% on the year.
The old base was small, and the IFR said so itself. Its November 2024 release described China as having a manufacturing workforce of around 37 million people. The detailed method sits in the paid report, so which Chinese statistic that was is not public. An outside analyst, Amelia Michael, made a guess in a Substack post in February 2026. She noted that 37 million is close to the 35.78 million employed in manufacturing at "urban non-private units" in China's 2023 statistical yearbook, a category that leaves out private and rural firms. Dividing about 1.76 million robots by the 2023 economic census figure of about 105 million manufacturing employees, she got about 167. The IFR's new number is 166. That's her estimate, and the IFR has not published its method. Still, the match is hard to ignore.
Fig.1In the IFR's April 2026 release, 2024 robot density was 1,220 in Korea, 818 in Singapore, 449 in Germany, 446 in Japan, 307 in the US and 166 in China. On the older employment base, China was reported at 470 for 2023. The robot counts did not shrink; the count of Chinese factory workers roughly tripled. Source: IFR, November 2024 and April 2026.
The world average moved too, from 162 in 2023 to 132 in 2024. The IFR does not explain the drop. My reading is that China holds about 43% of the world's 4.66 million operating robots, so tripling its worker count drags the global average down. If someone lines up the two years and writes that global automation went backwards, they've probably made a mistake.
Where China really is ahead
The numerator did not change. According to the IFR, China passed 2 million industrial robots in operation in 2024, about 4.4 times Japan's 450,500. Of the 542,000 robots installed worldwide in 2024, 295,000, or 54%, went into China. Japan installed 44,500, down 4%. Chinese suppliers now take 57% of China's own installations, up from about 28% a decade earlier (IFR, September 2025).
Japan's strength is on the supply side. IFR President Takayuki Ito said in July 2025 that Japan accounts for 38% of global robot production. Japanese factories automated early, their density is still in the world's top four, and most of those robots came from Japanese makers.
So the accurate headline is that China outbuilt Japan. For a Chinese robot arm maker, that also means Japanese factories are the hardest place to sell. The incumbents there are local, embedded and good. I once researched companies that had the same product and the same target customers as a set of competitors, and found their customer-acquisition logic was completely different. Treating every robot company as a rival of the Japanese majors is the kind of mistake I wrote about in picking the wrong competitors.
Where Chinese robot companies have an opening
In my view, the opening sits where robot density doesn't look. Warehouses, logistics, services and care. These are the sectors where Japan can't find enough people, and where Japanese incumbents are less entrenched.
One recent deal shows what entry looks like in practice. According to LOGI-TODAY, a Japanese logistics trade outlet, and English-language robotics news citing the company's own release (which I could not open directly), Bitcoin Japan, based in Sumida, Tokyo, signed an exclusive agreement on October 16, 2026 to distribute six UBTECH models in Japan, including the Walker S2 and Walker C1 humanoids and the Cruzr S2 service robot, with an initial focus on manufacturing and logistics. The exclusivity runs 36 months from the date the first model completes Japanese certification, and keeping it depends on conditions in the contract. Until certification, the robots can be supplied only for research, testing, data collection and demonstrations. No prices or volumes were disclosed as of October 2026.
Read the terms as an operating plan. The sales clock doesn't start until certification. Before that, someone still has to find pilot sites, install the robots, keep them running and fix them. If the distributor has no field engineers, the exclusivity will not produce sales. The usual reasons a distributor in Japan isn't selling get heavier when every unit has to be installed on a live site and pass a safety sign-off.
That shapes the first hires. A Japan entity for a robot company probably needs a field service engineer, someone who knows the certification and safety-standard process, and a person who can see what the distributor is actually doing, before it needs a big sales team. Japan is an attractive market that takes a long time to pay back, which is the same tension behind Japan's low inward FDI.
What I take from all this is mostly a set of reading habits. To compare China with Japan, look at installations and operating stock, not density. Read Japan's density with its falling factory headcount in mind. For service robots, go find a different statistic. I have not seen the IFR's full method, which sits behind the paywall, so treat my reading of the world average as a reading. And when a slide says China overtook Japan, ask what it was divided by.
Sources
- IFR, Robot Density Surges in Europe, Asia, and Americas (Apr 8, 2026): 2024 density Korea 1,220, Singapore 818, Germany 449, Japan 446, US 307, China 166, world 132
- IFR, China Overtakes Germany and Japan in Robot Density (Nov 20, 2024): 2023 China 470, Germany 429, Japan 419, world 162; China's manufacturing workforce given as around 37 million
- IFR, Global Robot Demand in Factories Doubles Over 10 Years (Sep 25, 2025): 2024 installations world 542,000, China 295,000 (54%), Japan 44,500; operating stock world 4,664,000, China over 2 million, Japan 450,500
- IFR, Japan's Car Industry Has Highest Robot Installations in Five Years (Jul 14, 2025): Japan 38% of global robot production
- Amelia Michael, China's Robot Density is Overstated (Substack, Feb 25, 2026): outside reconstruction of the old base
- LOGI-TODAY (Oct 19, 2026): Bitcoin Japan and UBTECH exclusive distribution agreement, based on the company announcement
- Origin of Bots (Oct 2026): same agreement, citing Bitcoin Japan's GlobeNewswire release
Shorter notes that don't make it into a full article go on LinkedIn. Follow me there.