Japan's Outward FDI Is 6.6 Times Its Inward FDI
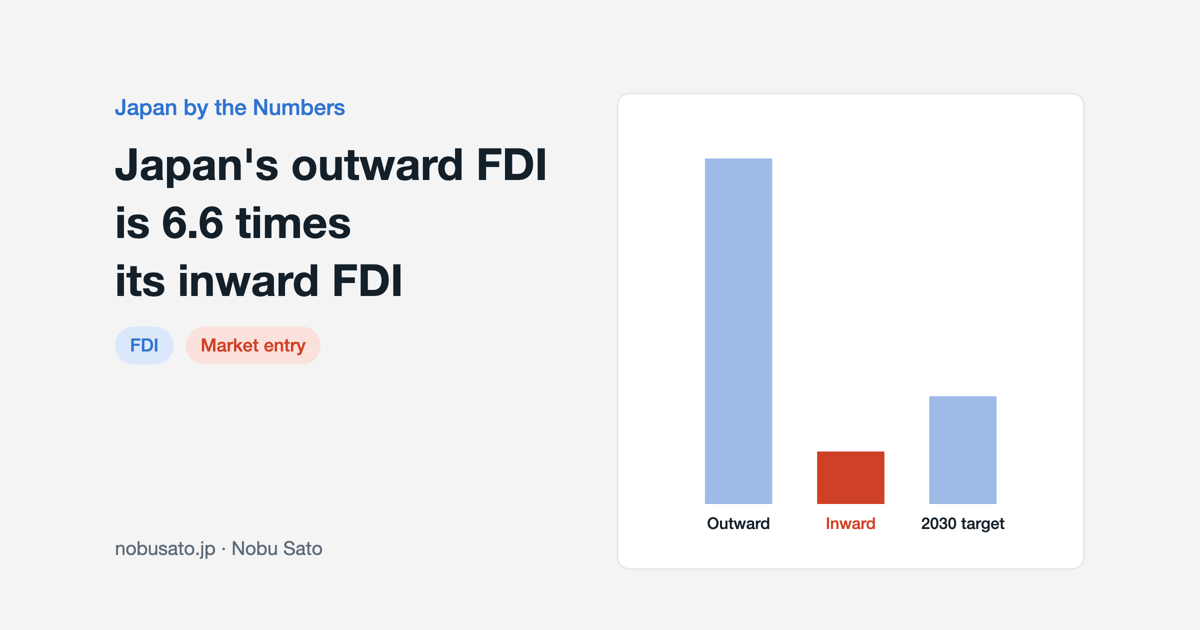
For every yen foreign companies have invested directly in Japan, Japanese companies have invested about 6.6 yen abroad. At the end of 2025 the outward direct investment stock was ¥384.5 trillion and the inward stock ¥58.6 trillion, according to Japan's Ministry of Finance and the Bank of Japan.
That gap tells you something practical if you run a foreign company's entity in Japan. Japan is very good at going out. It has far less practice at being gone into.
How big is the gap between outward and inward FDI?
The Ministry of Finance and Bank of Japan publish the International Investment Position of Japan every year. At end-2025, direct investment assets (Japanese companies' holdings abroad) stood at ¥384.535 trillion. Direct investment liabilities (foreign companies' holdings in Japan) stood at ¥58.562 trillion. The ratio is about 6.6 to 1, the same as at end-2024, when the figures were ¥352.8 trillion and ¥53.5 trillion.
In one year the outward stock grew by ¥31.7 trillion. The inward stock grew by ¥5.1 trillion.
One caution before reading too much into that. These are yen figures, and a weak yen inflates the yen value of assets held abroad. Part of the outward growth is currency, so it does not mean Japanese firms poured ¥31.7 trillion of fresh money overseas in 2025. My read is that even with the currency effect stripped out, a gap of roughly six times would still be there.
Fig.1At end-2025 Japan's outward direct investment stock (¥384.5 trillion) was about 6.6 times its inward stock (¥58.6 trillion). Even the 2030 target of ¥120 trillion would be less than a third of the outward stock. Sources: MOF and Bank of Japan, International Investment Position of Japan (end-2025); Cabinet Office, Program for Promoting FDI in Japan (2026).
What going out looks like: Nippon Steel and U.S. Steel
The easiest way to feel the size of the outward side is Nippon Steel. It completed its acquisition of U.S. Steel in 2025 and committed to invest $11 billion in the U.S. by 2028. On October 22, 2026, U.S. Steel said it would spend about $3 billion on a new hot-strip mill at its Mon Valley Works in Pennsylvania, aiming to start production in the second half of 2029 (Jiji Press and Manufacturing Dive, October 23, 2026).
The detail I keep coming back to is the budget. The plan was up to $2.5 billion. Jiji reports that higher labor costs and inflation pushed it to about $3 billion, roughly 20% more.
A company that can write an $11 billion cheque still finds that people and time move the number. Foreign companies coming into Japan hit the same wall, usually at a much smaller scale and with much less room to absorb it.
Why is Japan's inward FDI so low relative to GDP?
Scaled to the economy, the inward side stays small. Kozo Kiyota of RIETI, writing in the Nikkei's Keizai Kyoshitsu column on December 4, 2025, put Japan's inward FDI stock at 8.5% of GDP at end-2023, 192nd of 198 economies in UNCTAD data. The same piece cites 46.1% for the U.S., 19.9% for China and 16.8% for South Korea, without stating the year.
The exact figure depends on the method. Richard Katz, writing in Toyo Keizai's English edition in June 2025, noted that Japan's ratio is about 9% on the Ministry of Finance basis for 2024, and 5.9% under IMF and OECD rules that strip out intra-company loans. So you will see anything from 5% to 9% quoted. Whichever you use, Japan sits at the bottom of the major economies.
I covered the "good market, hard to enter" side in why Japan's inward FDI is low, and the day-to-day friction in what foreign companies struggle with in Japan. The government's own 2026 program lists foreign-language administration and securing talent among the issues foreign firms raise.
Can Japan reach its ¥120 trillion target at the current pace?
As of October 2026, the government target is an inward FDI stock of ¥120 trillion by 2030 and ¥150 trillion as early as possible in the early 2030s. The targets were set in the 2025 program and kept in the 2026 one.
From ¥58.6 trillion at end-2025, reaching ¥120 trillion by 2030 means adding about ¥61 trillion in five years, or about ¥12 trillion a year. The 2025 increase was about ¥5.1 trillion. On my arithmetic, the pace would need to more than double.
And if Japan hits ¥120 trillion, the inward stock would still be less than a third of today's outward stock. The gap would narrow. Japan would still be far better at investing abroad than at being invested in.
What the gap means for hiring in a foreign entity
This part is my view, not a statistic. I think a 6.6-to-1 imbalance leaves a mark on the talent market. Many Japanese managers have set up or run overseas subsidiaries from headquarters. Far fewer have spent years inside a foreign company's Japan entity, the small office a long way from HQ.
A foreign company entering Japan once came to me with questions about incorporation procedures. What actually kept them stuck was their first hire: who, at what pay, how to interview, how to attract the person, and how that person would talk to headquarters. The procedures were searchable. The hire was not.
I have a hypothesis here, with no data behind it yet. Japanese candidates who have worked in a Japanese company's overseas subsidiary may be a better fit for a foreign entity in Japan than their CVs suggest. They know the HQ-and-outpost relationship, just from the other side.
If Nippon Steel's budget can move 20% on labor and inflation, a Japan entry plan that treats hiring as a line item will move more. I would build the plan backwards from the first three hires and let the timeline follow.
Sources
- Ministry of Finance and Bank of Japan, International Investment Position of Japan, end-2025: direct investment assets ¥384.535 trillion, liabilities ¥58.562 trillion
- Council for Promotion of Foreign Direct Investment in Japan, Program for Promoting FDI in Japan (2026), July 2, 2026: end-2025 stock about ¥58.6 trillion; targets ¥120 trillion (2030), ¥150 trillion (early 2030s)
- Kozo Kiyota (RIETI), Nikkei Keizai Kyoshitsu, December 4, 2025 (Japanese): inward FDI 8.5% of GDP at end-2023, 192nd of 198 (UNCTAD)
- Richard Katz, Japan Still 196th In Inward FDI, Toyo Keizai, June 2025: 5.9% under IMF/OECD rules
- Jiji Press via nippon.com, October 23, 2026: about $3 billion hot-strip mill, original plan up to $2.5 billion
- Manufacturing Dive, October 23, 2026: U.S. Steel board approves nearly $3 billion, production late 2029
Shorter notes that don't make it into a full article go on LinkedIn. Follow me there.