Japan's wages: up forty times, then flat for thirty years
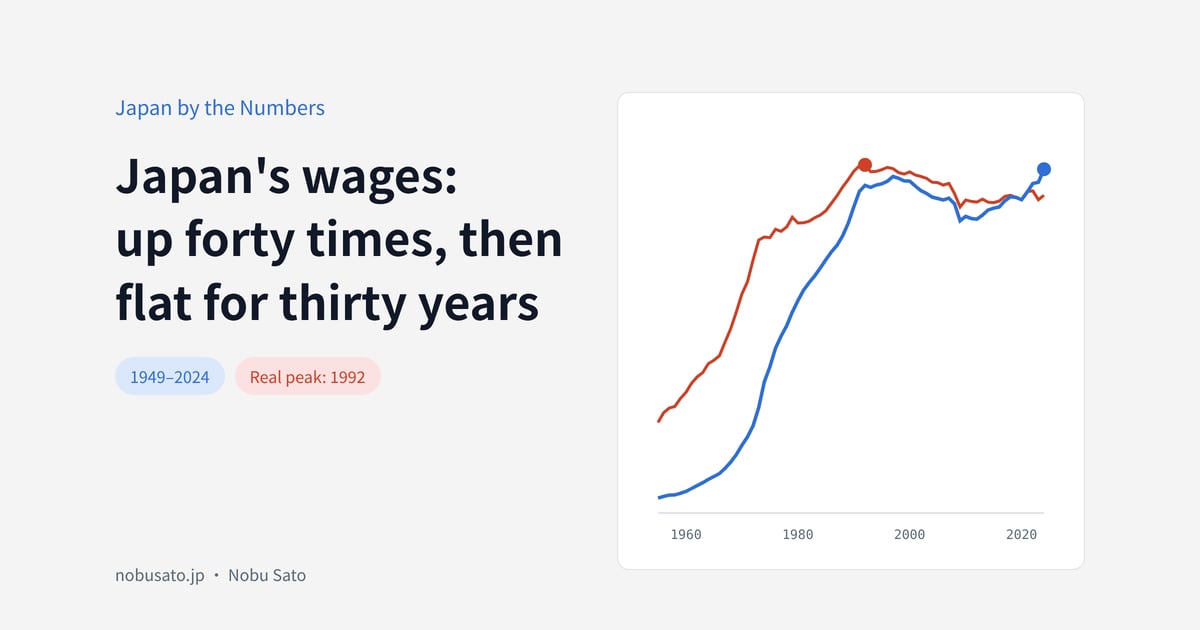
When executives set pay in Japan, the first question is always what the market rate is for the role. There is an answer. Behind it sits an eighty-year curve, and pay set without looking at that curve tends to be aimed at a market that no longer exists.
I put three public datasets side by side, from the National Tax Agency, the labor ministry and the statistics bureau, and read the curve end to end. It falls into three stretches. Each one has a direct consequence for how you set pay today.
1949 to 1974: annual pay up sixteen times
The National Tax Agency's survey of private-sector pay starts in 1949 and records the average annual pay of people who worked a full year at a private company. In 1949 it was ¥111,000. In 1955, ¥207,000. In 1970, ¥940,000. In 1974, ¥1.82 million.
Sixteen times in twenty-five years, in nominal terms. Even after inflation, real pay tripled between 1955 and 1974. Raises came every year. The spring wage round, shunto, delivered 18.5% in 1970, 20.1% in 1973, and 32.9% in 1974, the oil-shock year.
The expectations that generation formed are still built into Japanese pay systems: seniority-based pay, automatic annual increments, wages that only go up. These aren't culture so much as habits that twenty-five years of data created.
1975 to 1997: slower, but still rising
After the oil shock, shunto settlements dropped to single digits and held at 4 to 7 percent through the 1980s. 5.94% in 1990, 5.65% in 1991. Average annual pay rose from ¥2.03 million in 1975 to ¥4.67 million in 1997.
Real pay peaked in 1992, at ¥4.83 million in 2020 prices. Nominal pay peaked a few years later, in 1997, at ¥4.67 million.
Fig.1National Tax Agency average annual pay (full-year employees) and the same series in 2020 prices, 1955–2024. Real pay peaked in 1992 and is still 8.7% below that in 2024.
1997 to 2023: nominal up 2%, prices up 11%
This stretch is the entire working life of most Japanese employees today.
Average pay was ¥4.67 million in 1997, fell to ¥4.06 million after the 2009 financial crisis, then crawled back to ¥4.60 million in 2023, still below 1997. Shunto settlements slid from the 3% range in the 1990s to 1.66% in 2002, then sat between 1.6% and 2.4% for twenty years. Automatic increments survived; base pay barely moved.
Prices were flat over the same period, so life didn't get worse. It didn't get better either. The Cabinet Office's 2025 economic white paper is blunt: wages were flat from 1994 to 2014, and falling for middle-aged workers. Over the forty years from 1984 to 2024, pay for workers in their early twenties rose 72.6% cumulatively. For workers in their early forties, 38.7%. The lifetime earnings a new hire could expect, measured as a multiple of starting pay, fell from 62.2 times in 1984 to 54.4 times in 2024.
In other words, for thirty years Japanese companies gave what little increase there was to the young and held down the middle. What that means for hiring comes later.
Fig.2Shunto settlements at major companies (labor ministry), 1965–2025. 32.9% in 1974, around 2% for twenty years after 2002, back above 5% since 2024.
Since 2024: the first real raises in thirty-three years
Shunto settled at 3.60% in 2023, the first time above 3% since 1994. Then 5.33% in 2024 and 5.52% in 2025, two straight years above 5%, which hadn't happened since 1991. Average pay in 2024 reached ¥4.78 million, finally above 1997.
One thing to see clearly, though. Prices rose more than 8% between 2022 and 2024. In 2020 prices, 2024's average pay is ¥4.41 million, still 8.7% below the 1992 peak and roughly back at 1990 levels. A nominal record, and in real terms a return to thirty-four years ago. The Cabinet Office's phrasing is that real wages stopped falling in FY2024 but haven't yet consistently outpaced prices.
Starting pay has moved faster. Labor ministry data puts starting monthly pay for male university graduates at ¥194,000 in 1995, almost unchanged for twenty-five years, ¥213,000 in 2019, then ¥265,000 in 2025, up 24% in six years. The price at the entrance is being reset. The price in the middle hasn't caught up.
Fig.3Starting monthly pay for male university graduates (labor ministry), 1976–2025. Almost flat from 1995 to 2019, then up 24% in six years. From 2020 the survey basis changed to individual records.
What this curve means for anyone setting pay in Japan
Three things.
First, any pay benchmark from before 2022 has expired. Many foreign companies entering Japan reference market rates from a few years back. Those rates hadn't moved in thirty years, and the market started moving in 2023. Bring 2021 numbers to a 2025 candidate and they'll conclude you haven't done your homework.
Second, the middle is undervalued. Japanese workers around forty have had their pay held down for thirty years, and the skill and experience are still there. I once hired an excellent person at double their previous salary, and the number was still on the low side of the market. Their previous employer hadn't seriously reviewed their pay in twenty years, and they had no idea what they were worth. There's more than one person like that. If you want to hire experienced people out of Japanese companies, this is a window, and it won't stay open.
Third, the expectation of raises is back. After two years of 5%, candidates assume pay goes up every year. A foreign company that imports HQ's performance-decides-everything, base-can-stay-flat design will have it read as a pay cut in Japan. That isn't greed. The reference point moved. I wrote about money and retention in A 50% raise, and he still left, and about how to judge how many people a role has left in the market in A talent map is not a list.
What I haven't worked out
How long this round of raises lasts, I don't know. The main driver is the labor shortage; inflation only lit the match. The shortage won't change soon, so I lean toward it continuing. But the shunto figures that look so good come from the labor ministry's set of major companies: 390 firms with capital of ¥1 billion or more, a thousand-plus employees and a union. I haven't found a series of the same length for small and medium companies, where seventy percent of Japan's workforce is.
What year was your company's Japan pay benchmark set?
Shorter notes that don't make it into a full article go on LinkedIn. Follow me there.