A good market that is hard to enter: how low Japan's inward FDI is
Series「Five numbers to read before entering Japan」 · Part 1 of 5
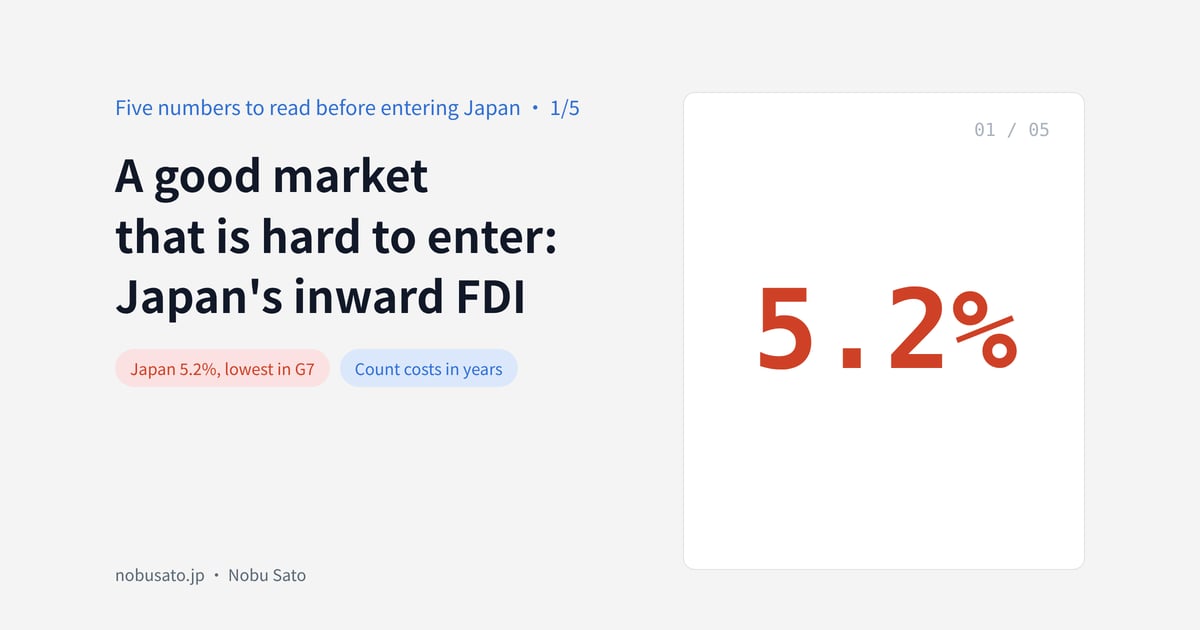
There is one number every company considering Japan should look at first: foreign direct investment stock in Japan as a share of Japan's GDP. At the end of 2024, on the OECD's basis, it was 5.2%. The same year: Canada 82%, the UK 72%, the US 40%, France 31%, Germany 27%, Italy 21%. Japan is the lowest in the G7, and not by a little.
Getting the number right
There are two ways to count it. JETRO uses the asset/liability principle, which includes money that Japanese companies' overseas subsidiaries invest back into their parents: 53.3 trillion yen at end-2024, or 8.7% of GDP. The OECD uses the directional principle, which strips that out: 5.2%. Both are correct; the difference is the numerator. On either measure, Japan sits at the bottom of the major economies.
The Japanese government knows this. Its FDI promotion council raised the 2030 stock target from 100 to 120 trillion yen. Even if achieved, that puts the GDP share in the low double digits, still far from the rest of the G7.
Fig.1Inward FDI stock as a share of GDP, G7, 2024, OECD basis. Japan: 5.2%. On JETRO's asset/liability basis it's 8.7%; the ranking doesn't change.
The usual reading: Japan is closed
Most people see this number and conclude that Japan is closed: heavy regulation, slow procedures, hostility to outsiders. That reading made sense in the 1980s. It doesn't hold today. Japan's restrictions on foreign entry rank among the looser ones in the OECD's index, a company can be registered in weeks, and tax and visa procedures are clear and predictable.
Besides, if regulation were the problem, procedures would be the top complaint. In What foreign companies struggle with most in Japan, the JETRO and METI surveys say otherwise: talent ranks in the top three, procedures ninth. Companies that have entered don't complain about the door. They complain about what comes after it.
The method's reading: what's hard is time and trust
The more plausible explanation for low FDI stock is that the payback period for entering Japan is so long that many companies leave before breaking even, or never come.
Japanese customers switch suppliers slowly, channels are held inside existing relationships, and a new brand often takes years from first visit to first order. That isn't regulation. It's how trust gets built. A Japanese customer isn't evaluating your product so much as whether you'll still be here in five years. A market with foreign capital at 5% of GDP is also a market where "foreign companies come and go" has been confirmed over and over, so the caution has an empirical basis.
So the entry decision this number changes is the unit of cost accounting. Most HQs measure Japan's return by quarter or fiscal year; Japan's payback period is three to five years. Use the wrong unit and the project is judged a failure in year two.
The action: step one is a map, not a registration
If costs run in years, the first year's money shouldn't go to an office and a legal entity. It should go to figuring out where those three to five years will be fought.
Concretely, draw the market map first: who the real competitors are, which channels are held by whom, who customers buy from and why. That's the subject of Picking the wrong competitors is worse than having none. Once the map exists, decide whether to register, in what form, and who the first hire is. Reverse the order, register the entity, hire the people, and spend two years discovering the market's entrance isn't where you thought, and those two years are part of why the FDI stock is so low.
Check yourself
On what payback period was your Japan budget approved? If the answer is one year, this number tells you that you're going to be the part of the denominator that leaves.
Sources
- ジェトロ対日投資報告2025 第2章第1節 対日直接投資額の推移(2024年末残高53.3兆円、対GDP比8.7%)
- OECD, FDI positions by partner country (inward FDI stock as % of GDP, 2024; G7 comparison)
- 内閣府 対日直接投資推進会議「対日直接投資促進プログラム2025」(2030年目標)
In this series
Next:The country with the most century-old companies: why newcomers can't move customers
Shorter notes that don't make it into a full article go on LinkedIn. Follow me there.